Before releasing goods or completing paid work, confirm the payment in the relevant transaction record—not only in a customer’s message or screenshot. Match the confirmed amount, status, payment reference or transaction ID to the correct order, invoice or service, then record the decision before fulfilment.
This simple routine helps Nigerian small businesses, freelancers, startups and independent professionals avoid releasing products or deliverables against a payment that is still pending, failed, reversed or connected to a different transaction.
Is a customer’s payment screenshot enough proof?
Usually, no. A screenshot can show that a customer attempted to make a payment or received a payment message, but it does not by itself prove that your business has received usable funds.
A screenshot may also be:
- For a different amount
- Connected to another order or customer
- Showing a pending rather than completed transaction
- Missing the transaction reference or ID
- Old or taken before a status changed
- Difficult to match to your own payment record
Treat customer-submitted evidence as a useful starting point, not the final release approval. The stronger confirmation is the transaction record available through the relevant payment provider or business payment account.
The practical rule is:
Do not release goods or complete the final handover until the payment is confirmed in the record you rely on for your business.
This does not mean assuming that every customer is acting dishonestly. It means separating what the customer says happened from what your business can verify.
A five-step payment verification routine
1. Identify exactly what the payment is for
Start with the commercial context. Before checking a transaction, know which customer, order, invoice, project or appointment the payment should relate to.
Record or confirm:
- Customer name or identifier
- Order, invoice or project reference
- Product or service involved
- Expected amount and currency
- Whether the payment is a deposit, balance or full amount
- What should happen after confirmation
This first step prevents a genuine payment from being assigned to the wrong order. It is particularly important when several customers are paying similar amounts on the same day.
For example, a Nigerian clothing business may receive two payments for similar garments. Both customers may send messages saying “paid”, but the business still needs to identify which payment belongs to which order before preparing either item for delivery.
2. Compare the expected amount with the transaction
Check the amount shown in the relevant payment record against the amount expected for the order or service.
Do not approve fulfilment automatically when:
- The amount is lower than expected
- The currency is different from the agreed currency
- The payment appears to cover only a deposit
- A fee or deduction changes the amount received
- The customer has combined several payments without clear detail
- The payment appears duplicated
An amount match is important, but it is not enough on its own. Two unrelated transactions can have the same value. That is why the amount should be checked alongside the customer, purpose, date, reference and status.
If the customer has paid a deposit rather than the full balance, the correct action may be to continue only with the stage covered by the deposit. Your payment terms should make that distinction clear.
3. Check the transaction status
Look for the current status in the relevant payment record. Common terms include:
- Successful or completed: the transaction has reached a completed status according to the relevant system.
- Pending: the payment has started but has not reached a final status.
- Failed: the transaction did not complete successfully.
- Reversed: the transaction was cancelled or returned after being initiated or recorded.
A customer’s screenshot may show a message such as “successful”, but your business should still check the record it uses to confirm receipt. Different records may describe different stages of the payment journey.
A pending transaction is not the same as a confirmed receipt. It may still change to a completed or failed status. Until the position is clear, avoid treating the payment as final.
If the payment is pending, learn what to do when a digital payment is pending in Nigeria rather than asking the customer to make another payment immediately.
4. Match the reference or transaction ID
A payment reference connects a payment to a business purpose such as an order, invoice, project or appointment. A transaction ID is an identifier assigned to the transaction by the payment system or provider.
They serve different purposes:
- Your order or invoice reference explains what the customer is paying for.
- The provider’s transaction ID helps locate the payment in the relevant transaction record.
- The customer’s name or account information helps connect the payment to the person or business involved.
- The date and amount help confirm that the transaction fits the expected payment.
Where available, compare the customer-provided reference or transaction ID with your own record. If a customer sends an ID that cannot be found, do not guess that the payment is genuine or that the record has simply been delayed. Check the details carefully and use the appropriate provider channel if follow-up is necessary.
References should not contain unnecessary private information. A simple order code or invoice number is usually easier to recognise and safer to share than sensitive personal details.
5. Record the decision before fulfilment
After checking the payment, record what you found and what action you approved.
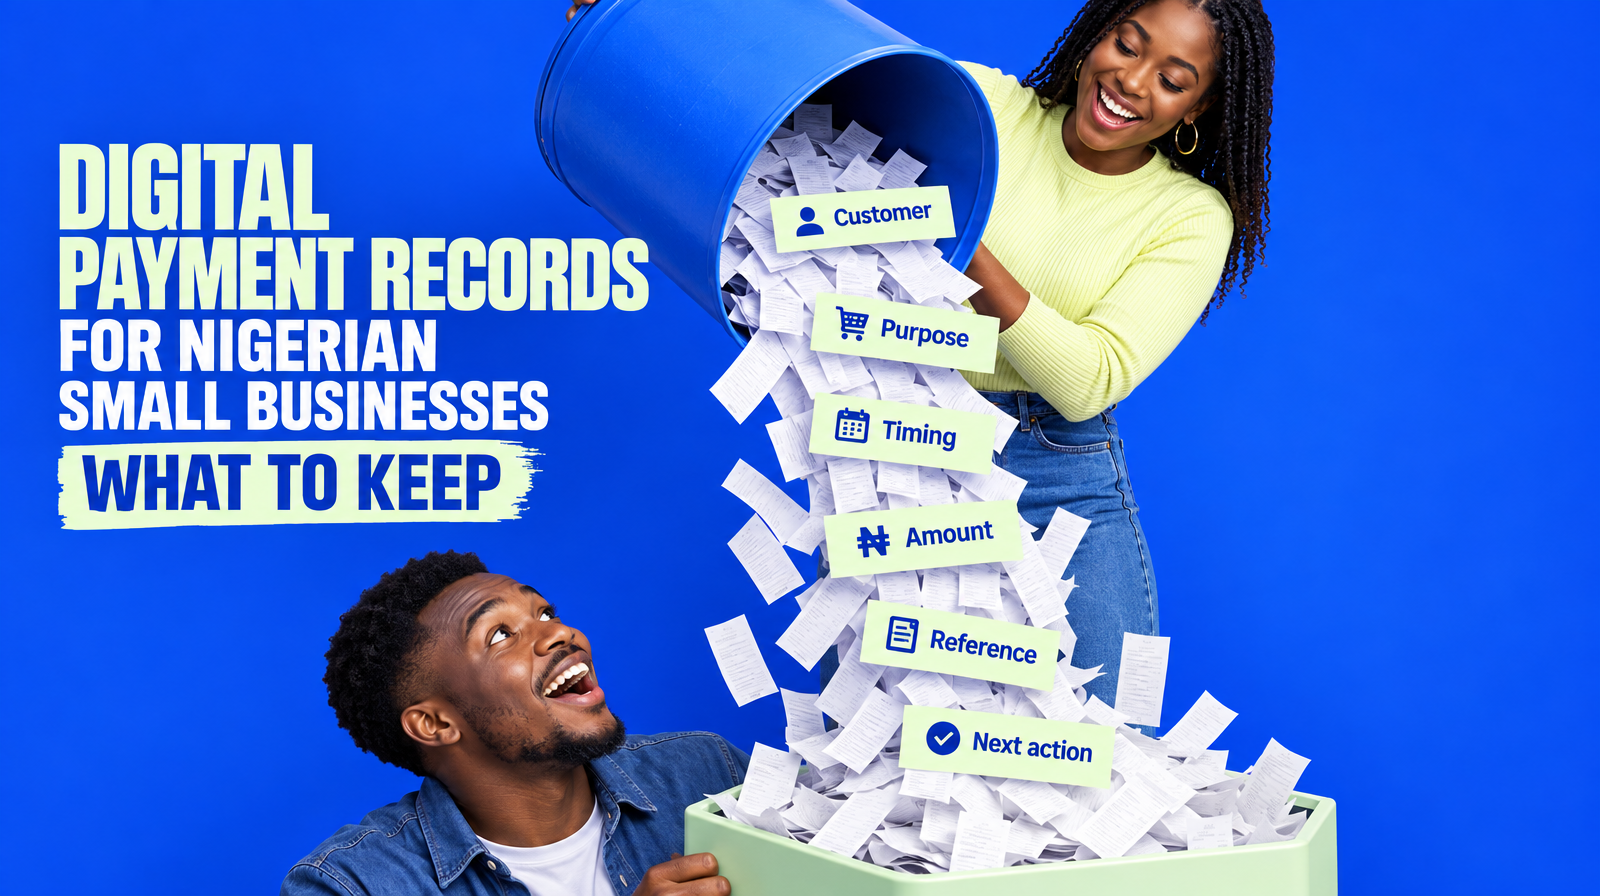
A basic payment-verification record can include:
- Date and time checked
- Customer or payer
- Order, invoice or project reference
- Expected amount
- Amount shown as received
- Currency
- Payment method or channel
- Payment reference
- Transaction ID
- Current status
- Decision: release, hold or investigate
- Staff member who checked it
- Next action, if any
This record does not need to be complicated. A spreadsheet, order-management document or clearly organised digital record may be enough for a small business. The purpose is to make the decision traceable and reduce repeated questions between staff.
For a fuller record-keeping framework, see Digital Payment Records for Nigerian Small Businesses: What to Keep.
When should a business wait?
Wait before releasing goods or completing the final service handover when any important part of the transaction is unclear.
That includes situations where:
- The status is pending
- The payment cannot be found in the relevant record
- The amount does not match the order
- The reference points to another customer or order
- The customer has sent only a screenshot
- The payment appears failed or reversed
- The customer has paid only part of the agreed amount
- The record shows conflicting information
- The business cannot confirm that funds were received
Waiting is especially important when fulfilment creates an immediate cost or when the product is difficult to recover after release. Examples may include a customised item, a dispatched parcel, a completed design file, a repaired appliance ready for collection or a service that cannot realistically be undone.
A business can set different release rules for different types of work. A low-value, immediately delivered service may have a different process from a high-value product order or a custom project. The important point is to decide those rules in advance rather than improvising under customer pressure.
What to do when the customer says payment was successful
Respond professionally and keep the conversation factual. Do not accuse the customer, promise a release time you cannot confirm or ask for a duplicate payment before establishing what happened to the first attempt.
A useful message could be:
Thanks for sending the payment details. We are checking the transaction against your order now. The payment is not yet confirmed in our business record, so we will hold fulfilment until the status and amount are matched. We will update you once the record is confirmed. Please keep the transaction reference available in case the payment provider requires it for follow-up.
If the payment is pending, explain that the order remains on hold until the transaction reaches a final status. If the payment cannot be located, ask for the relevant details again without requesting sensitive information such as passwords, personal identification numbers or one-time security codes.
The customer should know three things:
- What has been checked
- What remains unconfirmed
- What action will happen next
Clear communication protects the customer relationship while maintaining a sensible release boundary.
Practical examples for Nigerian businesses
Product order
A customer orders a phone accessory, shares a payment screenshot and asks for dispatch. The business checks the order reference, expected amount and transaction record. The record shows a pending payment.
Decision: Do not dispatch yet. Record the pending status, tell the customer that fulfilment is on hold and review the transaction again through the appropriate channel.
Freelance deliverable
A Nigerian graphic designer completes a client project after agreeing that the remaining balance is due before the final files are handed over. The client sends a screenshot, but the transaction ID does not match the designer’s record.
Decision: Keep the final handover on hold. Ask the client to confirm the transaction details and check the payment record before sending the completed files.
Service business
A repair professional has completed work on an appliance. The customer says payment was made, but the business record shows an amount that does not match the agreed balance.
Decision: Do not treat the payment as fully settled. Confirm whether the amount was a deposit, partial payment or an error, then agree the next step before final collection.
Custom order
A tailor receives a payment that matches the expected amount but has no clear customer or order reference. Several orders are active.
Decision: Do not rely on the amount alone. Match the transaction using the payer information, date and customer communication before assigning it to a specific garment or releasing the order.
A release-before-fulfilment checklist
Use this checklist before sending goods, sharing final files or completing the last stage of a paid service:
- I know which order, invoice, project or service the payment is for.
- The customer or payer matches the transaction record.
- The amount and currency match what was expected.
- The payment status is final and clear.
- The payment reference or transaction ID has been checked where available.
- The transaction is not marked pending, failed or reversed.
- Any deposit or balance requirement has been satisfied.
- I have recorded the verification result.
- The release decision has been communicated to the person responsible for fulfilment.
If any critical box remains unchecked, place the order or deliverable on hold until the uncertainty is resolved.
Build verification into the wider payment process
Payment verification works best when it is connected to the rest of the customer journey. Give each order, invoice or project a clear reference. Tell customers what information to share after paying. Define when goods, files or completed services will be released. Keep payment records connected to the work they relate to.
This is different from reconciliation. Reconciliation is the broader process of comparing expected and actual transactions, often after business activity has taken place. Payment verification is the immediate operational decision that happens before fulfilment. For the wider review process, see How to Reconcile Digital Payments for a Nigerian Small Business.
Boldswitch is a Nigerian fintech platform providing digital payment solutions for individuals and businesses. For Nigerian freelancers, SMEs, entrepreneurs and startups managing transactions online, a clear payment routine helps connect money movement with the work, order or customer commitment it supports. Boldswitch’s proposition, “Digital Payment Without Limits,” reflects its focus on digital payments for people and businesses ready to move.
Final takeaway
A customer’s payment message is not the same as confirmed receipt. Before releasing goods or completing work, verify the transaction in the relevant record, match it to the correct commercial purpose, check the amount and status, retain the reference or transaction ID, and record the decision.
When the payment is unclear, waiting is not poor customer service. A concise explanation and a consistent verification process can protect the order, the business record and the customer relationship.